Home>Credit Score>Specific Score Evaluations
Credit Score
Specific Score Evaluations
Table of Contents
First, understand what your credit score range actually means
Before you fixate on where you fall in a specific credit score range, step back and recognize that a number like a 770 credit score mean something very different depending on which version of the scoring formula a lender pulls. You would want to read about what a 770 credit score mean because it clarifies how that figure can unlock the most competitive mortgage terms while still varying in impact across auto or credit card applications. That 770 sits comfortably in the “very good” or “excellent” tier. This signals to a mortgage underwriter that you are an exceptionally low-risk borrower and likely to receive the most competitive terms available. That same three-digit figure can shift in interpretation when an auto lender or credit card issuer uses an older model or an industry-specific score that weights your history differently. Never assume one number tells the whole story across every application.
The context of the loan type and the specific scoring model matters just as much as the digits themselves. You would want to read about a 675 credit score because it sits right at the cusp between fair and good, making it a pivotal point where a small financial move can determine whether you qualify for prime rates or remain in the non-prime tier.
Because of this, it is useful to compare how different score levels land across the spectrum. The list that follows walks through what each commonly searched tier generally indicates about your borrowing profile and which financial products tend to open up at that level.
A lender reviewing a 615 credit score typically sees a borrower rebuilding after a recent setback, which places you in the non-prime or near-prime category where approval is possible but often comes with higher rates and an offsetting requirement like a larger down payment.
A 650 credit score is generally a fair credit score and is below the broader “good” range that starts around 670 in many common scoring models. You will not yet snag the rock-bottom APRs reserved for top-tier applicants.
Moving up the scale, a 660 credit score pushes you firmly into the prime space where lenders compete for your business rather than simply agreeing to take a chance on you.
Just a few points higher, a 671 credit score lands you in nearly the identical underwriting bucket as a 660, but you are now inching close enough to the next tier that a single on-time payment cycle or a small reduction in credit card utilization could tip you over the line.
At this level, you are a clear prime borrower, and the interest rate spreads between you and someone with a 720 credit score begin to shrink, especially on auto loans and personal loans where collateral or shorter terms reduce the lender’s risk.
Now consider a 720 credit score, which is generally good or prime and on the lower end of the good range. Reaching it puts you in the conversation for competitive rates on mortgages, auto financing, and personal loans. You can apply for a broad array of loans and credit card products with confidence, and you will likely see higher credit limits that help keep your utilization ratio low with minimal effort. The difference in total interest paid over a 30-year mortgage between a 720 and a 780 credit score can still amount to thousands of dollars, so do not stop optimizing just because you hit this popular milestone.
See how good or bad your score really is
Before you fixate on a single number, it helps to know where you actually stand on the credit spectrum. The most common FICO scoring models use a 300 to 850 range. Lenders group those numbers into broad bands that signal how risky you look on paper. Scores from 300 to 579 are considered poor. A score from 580 to 669 is fair. A score from 670 to 739 is good. A score from 740 to 799 is very good. Anything 800 to 850 lands in the exceptional tier.
Knowing those buckets lets you decode what would a FICO score of 810 be considered when you spot it in a credit monitoring app. It is firmly exceptional. That tier typically unlocks the lowest advertised rates and the most negotiating power on major loans.
Where it gets tricky is that a single number can feel drastically different depending on the product you are shopping for. An auto lender and a mortgage underwriter often pull different score versions. They weigh your history through separate filters. The questions below walk through a few specific score levels people commonly search. You can match the number on your own report to the right tier and set realistic expectations before you apply.
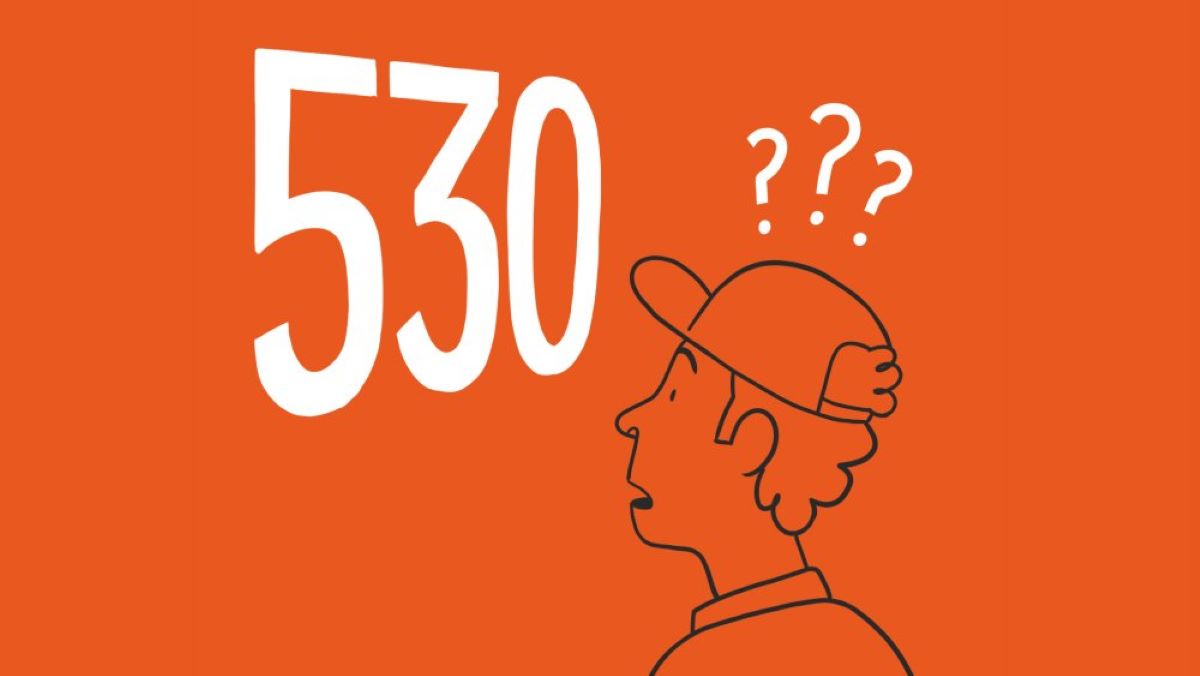
If you are rebuilding or just starting out, you might wonder how bad is a 530 credit score in practical terms. It sits deep in the poor range. Most prime lenders will decline an application at this level. You may still find approval through subprime specialists or secured products. The terms will almost always include steep interest rates, high fees, and a low credit limit. A score this low usually reflects recent missed payments, a default, or a high balance on a collection account. The path forward requires steady on-time payments and reducing outstanding debt. Progress can feel slow, but moving from poor to fair territory opens up dramatically better options.
You might also ask how bad is a 560 credit score if you are just a few points away from the next tier. It still falls in the poor band. The difference between 530 and 560 is often just a few months of positive payment history. You are on the cusp of a fair score. Lenders still see subprime risk, but you may qualify for entry-level credit cards or a small personal loan. The rates will still be high. The key is to avoid new hard inquiries until you cross that 580 threshold. Once you do, you unlock a wider range of starter products designed for fair credit.
As your profile strengthens, you start asking how good is a 690 credit score. This number lands squarely in the good range. It signals to lenders that you are a reliable borrower. Most credit card issuers will approve you for their mainstream rewards cards. Auto loans come with competitive rates rather than punitive ones. You may not get the rock-bottom APRs reserved for very good or exceptional scores, but you are no longer fighting against your credit. A 690 score often reflects a thin file or a single old blemish on an otherwise clean history. Adding a new positive tradeline and keeping utilization low can push you into the very good tier within a few months.
Once you cross into the upper tiers, you might wonder how good is a 790 credit score. This is a very good score that sits just below the exceptional cutoff. You will qualify for nearly every loan product on the market. The interest rates offered will be among the best available. A mortgage lender will see you as a low-risk applicant. An auto lender will give you top-tier promotional financing. The only practical difference between a 790 and an 810 is a slight margin on the interest rate. You should focus on maintaining this score by keeping old accounts open and avoiding late payments. There is no meaningful financial door that a 790 score cannot open.
Find out what you can actually get with your score
Once you know your general credit tier, the real question is what that number unlocks for a specific purchase. The same score lands differently depending on the loan type and the scoring model the lender pulls. If you are wondering what can I get with a 625 credit score, that score sits in the fair range and may meet the minimum for an FHA mortgage while falling just short of the threshold many conventional lenders want to see. Your home-buying power may be limited even while personal loan and auto loan offers start appearing.
Shift up to a 650 and a near-prime auto-loan approval may become a realistic path. If you are asking what car can I get with a 650 credit score, you can shop for a vehicle with more confidence even though the mortgage landscape still looks very different from what a higher score would encounter across the same applications. Similarly, if you are curious about what can you do with a 670 credit score, that number opens doors to better interest rates on credit cards and personal loans, while what can I get with a 683 credit score reveals even stronger approval odds for unsecured financing. At the lower end, what can you do with a 620 credit score helps you understand the minimum requirements for certain loans, and what can I get with a 648 credit score shows where you stand between subprime and fair territory.
Because each lender layers its own filters on top of the base number, your borrowing power changes not just with every point you gain but with every product category you explore. The comparisons below let you zero in on the exact score you are holding right now so you can set the right expectations before you apply for a specific type of credit.
- what can I get with a 625 credit score - What Can I Get With A 625 Credit Score
- what car can I get with a 650 credit score - What Car Can I Get With A 650 Credit Score
- what can I get with a 683 credit score - What Can I Get With A 683 Credit Score
- what can I get with a 648 credit score - What Can I Get With A 648 Credit Score
- what can you do with a 670 credit score - What Can You Do With A 670 Credit Score
- what can you do with a 620 credit score - What Can You Do With A 620 Credit Score
Look up scores in the mid-to-upper 600s
When your score sits in the mid-to-upper 600s, every point starts to matter. You are hovering right at the boundary where lender rate sheets shift. A jump from 660 to 680 can push you from a fair tier into a good tier on certain scoring models. This often means the difference between a standard APR and a noticeably lower one on an auto loan. The same two-digit swing might barely register on a mortgage application where the underwriter is using an older FICO version that draws its cutoff lines in different places.
This is also the range where it becomes essential to monitor your reports across all three bureaus. The myFICO app for Android can show you FICO Scores from Experian, TransUnion, and Equifax side by side. A 15-point gap between your highest and lowest bureau file could put one lender’s pull into a higher pricing tier while another’s lands just below it.
Small differences carry real weight here.
Checking your own credit will not hurt your score. The Experian Android app gives you an updated look every 30 days so you can track whether you are drifting closer to the line that unlocks better terms on the specific loan you want. This is where you must understand what lenders using a credit score of 600 mean when they set their approval thresholds, because the logic applies just as forcefully as you climb through the 600s.
Learn how to move your score up
Once you understand where your number lands on the spectrum, the next step is moving it higher. The tactics that improve 715 credit score are the same fundamentals that work at nearly any level: bring past-due accounts current, keep credit card balances well below their limits, and resist opening several new accounts in a short window. Paying down revolving debt so your utilization ratio drops can shift your score noticeably before your next statement cycle closes.
If you are rebuilding after a serious setback, one of the most common questions is will my credit score go up after chapter 7 falls off. The answer depends on what you have built in the meantime. A Chapter 7 bankruptcy generally stays on your report for ten years from the filing date and is removed automatically once that period ends. If you have spent those years adding on-time payments and keeping balances low, the deletion can clear the last major negative marker and produce a meaningful jump. Should the entry still appear past the ten-year mark, you can dispute it with each credit bureau by providing proof of the original filing date.