Investing
Dividend Investing
Table of Contents
- Before you start: dividend investing types and tax basics
- How dividends flow through financial statements
- Preferred stock and special dividend situations
- Accounting for dividends: debits, credits, and tax forms
- When popular stocks and ETFs pay
- Weekly payers, money markets, and less common schedules
- More payout frequencies across funds and firms
- Tracking suspended, resumed, and less common payers
- Reinvesting dividends at Fidelity
- Reinvesting dividends at Schwab and Vanguard
- Earning compound interest and growing your income
- More guides
Before you start: dividend investing types and tax basics
Before you commit a single dollar to dividend investing, it pays to understand that not all payouts are created equal in the eyes of the IRS. The most common split you will encounter is between qualified dividends, which enjoy lower long-term capital gains rates, and non-qualified dividends, which are taxed at your ordinary income bracket ranging from 10% to 37%. If you hold shares in a mutual fund that invests in municipal bonds, you might receive exempt interest dividends, while business owners and members of cooperatives face a unique category with patronage dividends. A key distinction to internalize early is the difference between dividends and interest, and you cannot fully gauge a portfolio’s performance until you grasp the interplay of capital gains vs. dividends. For pass-through entities, 199a dividends can offer a valuable deduction.
How dividends flow through financial statements
To understand where your income stream stands, you first need to know that payouts are not an expense on a firm’s profit-and-loss report, so you will not find common-stock cash returns listed as a line item there. When asking do dividends appear on the financial statement, the answer depends on timing: the cash flow statement captures the actual cash paid to shareholders under financing activities, while any declared but undistributed amount sits on the balance sheet as a current liability. You can confirm this by checking whether do dividends go on the balance sheet after a declaration date, where they appear as dividends payable until the cash actually leaves the business and the liability disappears, permanently reducing retained earnings in the equity section. If you are tracing the actual outflow of cash, do dividends go on the cash flow statement becomes the critical question, and the figure you want is listed as a negative number within the financing activities section. Because the income statement omits these shareholder payments entirely, you can calculate dividends from the income statement only indirectly by taking beginning retained earnings, adding net income, and subtracting ending retained earnings to solve for the dividend plug. Conversely, if you need to find net income with dividends, you reverse that same relationship by adding shareholder payouts back to the change in retained earnings to arrive at the profit figure. Pull the cash paid from the cash flow statement first, then verify declared amounts in the equity statement, and finally check the balance sheet for any lingering unpaid liability.
Preferred stock and special dividend situations
When a firm issues preferred shares, tracking where the payout lands means looking in a different place than you would for common stock. The declared amount is preferred dividends on financial statements within the stockholders’ equity section, which is why you need to know exactly where to look to avoid misreading your investment's true liability. Once the board authorizes a payment that has not yet gone out, that same figure shifts to the current liabilities side as an accrued dividend. You can think of the accrued dividend definition, how to calculate it, as the amount declared but not yet paid, which appears on the balance sheet as a current liability.
Things get less straightforward if you hold cumulative shares and the issuer hits a rough patch. With that structure, dividends are preferred dividends not declared when preferred stock is cumulative in a given period still accumulate in arrears and must be paid before common dividends, though they remain subject to declaration under the security's terms. The business must clear that entire backlog before any common shareholder sees a cent. To know what you are eventually owed, you calculate preferred dividends based on the share's stated dividend rate and par or liquidation value for each period missed, according to the security's terms. The exact terms always live in the prospectus.
In a different corner of corporate actions, you might encounter a credit dividend, which is a separate payout type that can affect your tax treatment and cost basis differently than cash or stock dividends.
Open your brokerage platform now and book the next shareholder meeting date for every stock you own. Arrive at the investor relations page, not the trading dashboard, and locate the record date. Skip the glossy annual summary and go straight to the preferred stock prospectus. Download it. Read the cumulative rights clause first. Set a calendar reminder three days before each ex-date so you never miss the cutoff. When you see a payout labeled as a return of capital, log it in your cost basis tracker immediately instead of treating it as income. If you hold a cumulative issue that suspends its regular payment, calculate your arrears that same afternoon and update your expected yield. For any new preferred offering, compare the fixed rate against the five-year Treasury and two investment-grade corporate benchmarks before you commit a single dollar. Check the issuer’s debt-to-equity ratio and its last four coverage ratios. If the coverage dips below 1.2x, reduce your position size. Reinvest each cash payment manually rather than relying on the platform’s automatic plan. That fractional treatment means you do not need to wait until you accumulate enough cash to purchase a whole unit. The fractional interest grows in lockstep with every reinvested dollar. Review your allocation weights every six months and rebalance when a single name crosses 5% of your income portfolio. Sell any holding where the issuer defers payments for two consecutive periods and the arrears exceed one full year of stated payouts. Park the proceeds in a floating-rate fund until you identify a replacement with stronger coverage. Track every ex-date, pay date, and record date in a single spreadsheet. Update your tax lot records quarterly so you never misclassify a return of capital at filing time.
- are preferred dividends on financial statements - Where Are Preferred Dividends On Financial Statements
Accounting for dividends: debits, credits, and tax forms
This is why you will never see these distributions reduce a firm’s net income on its profit-and-loss statement. The offsetting dividend credit sits on the other side of the journal entry. It represents either the cash that leaves your bank account upon payment or the liability you create under dividends payable at the declaration date. You already know that declared but unpaid amounts live on the balance sheet. Your task is simply to ensure that debit to retained earnings is matched by the correct credit and then cleared when the cash actually moves. For corporate filers, the paperwork shifts to the tax return, and you will want that guide on where to report dividends paid on form 1120 to avoid misstating your taxable income. You need to complete Schedule C for dividends, inclusions, and special deductions, with the total from that schedule's line 23, column (a), then feeding onto the main Form 1120 on line 4. The distribution itself does not appear as a separate expense line on the face of the return.
- are dividends recorded with debits - Why Are Dividends Recorded With Debits
When popular stocks and ETFs pay
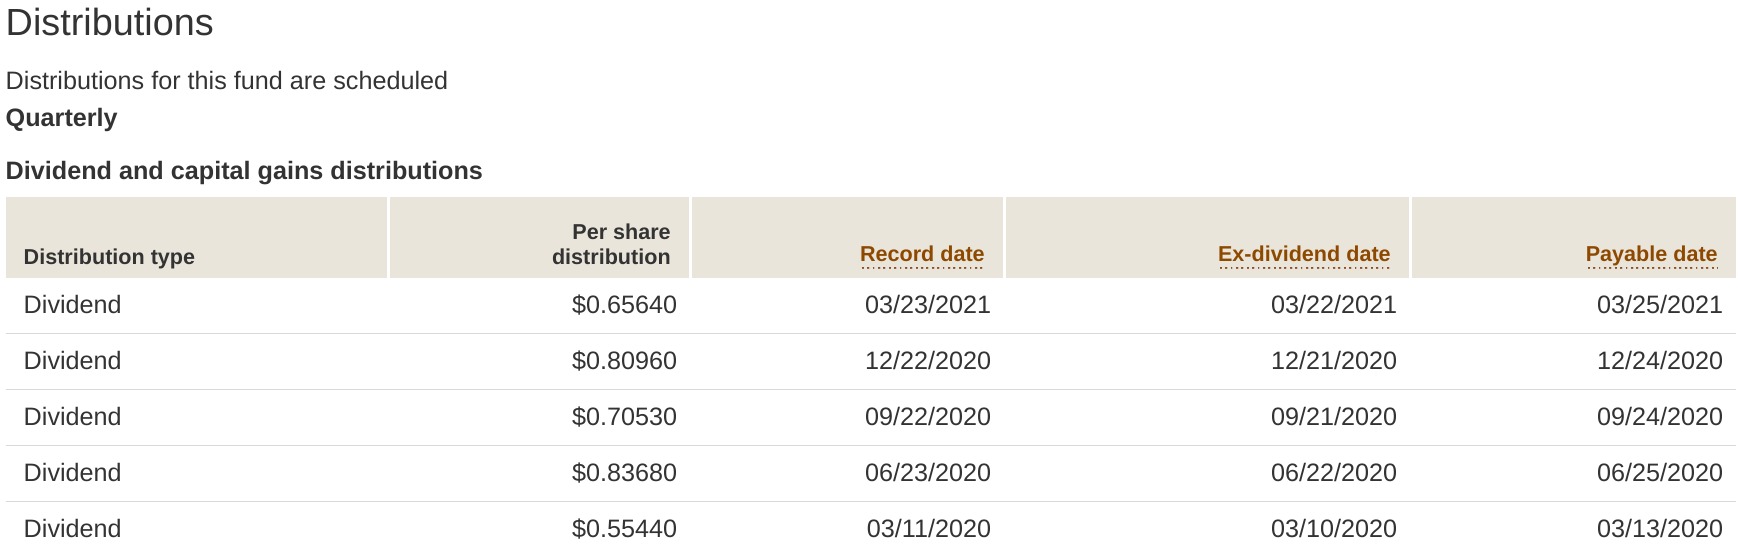
When you look for a payout schedule, the first thing to recognize is the split between equity dividends and fund distributions. Stock dividends follow quarterly company declarations. The answer to when does SCHD pay dividends depends on the board’s cycle rather than a fixed calendar date. The fund’s latest documented quarterly payout landed on Jun 29, 2026. Preceding payments arrived on Mar 30, 2026, Dec 15, 2025, and Sep 29, 2025. That quarterly rhythm is consistent, but the exact day drifts slightly across months. By contrast, money-market funds like SWVXX and SPAXX accrue interest daily and distribute it once a month. Buying in right before the monthly record date does not generate an immediate windfall the way an equity ex-dividend date does. Treating both structures identically leads to mistimed purchase expectations and unnecessary frustration when the cash does not land when you anticipated it.
Beyond SCHD, you will encounter the same question across a range of widely held positions. The group includes inquiries such as When Does VOO Pay Dividends?, When Does VTSAx Pay Dividends?, and How Much Does VYM Pay In Dividends. Several other core ETFs and individual names also appear. Each one follows its own declaration cadence. Pick the specific security you hold or are researching. Check its most recent distribution history. Do not assume a uniform schedule across the list.
To make that research practical, you need to know why each specific payout matters for your portfolio. For instance, if you are tracking a consumer-staples giant, you might wonder does pepsico pay dividends consistently, and the answer helps you gauge its reliability as a long-term income anchor. Similarly, when evaluating a tobacco heavyweight, asking does altria pay dividends reveals whether its high yield is sustainable or at risk. For blue-chip industrials, the question does ford pay dividends tells you if the automaker has restored its shareholder return after years of cyclical cuts. In the energy sector, does exxon pay dividends and does bhp pay dividends both signal how commodity cycles affect cash returns. For income-focused ETFs, does sphd pay dividends shows how a low-volatility strategy translates into monthly or quarterly income, while does sblk pay dividends highlights the payout from a shipping company tied to freight rates. On the financial side, does agnc pay dividends is crucial because mortgage REITs often cut distributions when interest rates shift. Meanwhile, does at&t pay dividends matters after the company spun off its media arm, and does vale pay dividends reflects Brazilian mining volatility. For growth names, does nike pay dividends confirms whether the sportswear brand still returns cash, and does pfe pay dividends tells you if the pharma giant maintains its payout despite patent cliffs. Finally, does fxaix pay dividends matters because the Fidelity 500 index fund distributes quarterly, but the amount varies with the S&P 500’s underlying yield, and does starbucks pay dividends is the key question for coffee investors seeking a growing yet modest yield. Each of these answers shapes your entry timing and reinvestment strategy, so verify the specific record date rather than relying on a general pattern.
- does fxaix pay dividends - When Does FXAIX Pay Dividends?
- does sphd pay dividends - When Does SPHD Pay Dividends?
- does starbucks pay dividends - When Does Starbucks Pay Dividends
- does ford pay dividends - When Does Ford Pay Dividends?
- does pfe pay dividends - When Does PFE Pay Dividends?
- does sblk pay dividends - When Does SBLK Pay Dividends?
- does agnc pay dividends - When Does AGNC Pay Dividends?
- does epd pay dividends - When Does EPD Pay Dividends?
- does exxon pay dividends - When Does Exxon Pay Dividends
- does at&t pay dividends - When Does AT&T Pay Dividends?
- does pepsico pay dividends - When Does PepsiCo Pay Dividends?
- does vale pay dividends - When Does Vale Pay Dividends
- does nike pay dividends - When Does Nike Pay Dividends
- does bhp pay dividends - When Does BHP Pay Dividends?
- does altria pay dividends - When Does Altria Pay Dividends
Weekly payers, money markets, and less common schedules
If you are searching for which stocks pay dividends weekly, the answer is more about fund structures than individual company shares because standard common stocks and most ETFs follow quarterly declaration cycles. Weekly dividend ETFs are described as distributing income every trading week, which usually means 51 or 52 payments per year, and the schedule is a feature of the fund wrapper, not a promise from a single operating business. When you broaden the question to what stocks pay dividends weekly, you will occasionally see references to certain REITs, BDCs, or peer-to-peer lending platforms that have paid weekly at various points, though those cases are far less common than weekly ETFs.
Money-market funds operate on an entirely different clock. Unlike equity dividends, their distributions accrue daily based on your settled cash balance and are paid out once a month. There is no ex-dividend date to trade around for a quick payout, and because the accrual resets daily, purchasing shares right before a record date does not capture a full month of income the way a quarterly stock dividend might. Treating a money-market position like a dividend stock leads to mistimed expectations about when cash will actually land in your account.
More payout frequencies across funds and firms
When you move beyond standard common stocks, the rhythm of payouts depends entirely on the structure of the entity you are holding. A traditional operating firm follows a board-driven cycle. Look up how often does UPS pay dividends and you will find a quarterly schedule. The investor relations team describes it as a consistent practice, though the exact record date shifts slightly from one announcement to the next. Mortgage REITs such as Annaly Capital Management operate on a similar cadence, but if you are weighing a real estate income play, you might first ask how often does NLY pay dividends to confirm whether that monthly check matches your cash-flow needs. This matters because investors sometimes mistake the steady income stream for a monthly payout structure. Business development companies can throw a different curve entirely. BDCs may adopt different rhythms depending on their portfolio cash flow, so checking how often does ARCC pay dividends helps you see whether that particular lender’s distributions align with your own bill-paying cycle. The answer depends on the specific fund, as stock ETFs and money-market funds may follow different schedules. For instance, if you are comparing cash-sweep options, you would want to know how often does SPAXX pay dividends before parking idle brokerage cash, just as you would verify how often does SWVXX pay dividends for a similar money-market alternative. Beyond these individual names, you will encounter a group of similar questions covering other widely held ETFs, REITs, and international firms. Each one follows its own announcement cadence, which is why you might research how often does VTI pay dividends to gauge the distribution frequency of a broad market index fund, or how often does QQQ pay dividends if you prefer a tech-heavy growth tilt. For those seeking high-yield exposure, understanding how often does SDIV pay dividends reveals whether that global dividend fund’s payouts are monthly or quarterly, and similarly, how often does Vanguard pay dividends clarifies the typical schedule for its equity index funds. Pick the specific security you hold or are researching and check its most recent payout history.
Tracking suspended, resumed, and less common payers
Dividend schedules are not permanent guarantees, and one of the most common points of confusion comes when a familiar payer goes silent. If you hold a stock that has paused its payout, watch for boardroom signals instead of a fixed calendar date. That kind of announcement is a discrete corporate action, not a gradual resumption, and a single press release can move a name from the suspended column back to the active one overnight.
Less common payers create a different tracking challenge. Some BDCs and REITs pay every three months but occasionally declare special distributions that break the pattern, while a handful of closed-end funds follow monthly or managed payout policies that adjust based on portfolio income. When a security falls outside the standard quarterly rhythm, pull the most recent notice directly from the issuer’s investor relations page rather than relying on a third-party calendar that may assume a generic frequency. Whether you are asking will ccl resume dividend payments or hunting for a payer with an unconventional schedule, the underlying principle remains the same: payout status is a current fact, not a historical pattern, and it changes only when a board issues a formal authorization.
Reinvesting dividends at Fidelity
When you reinvest dividends in Fidelity, the mechanics depend on whether you are holding full shares or a fractional position, but the Dividend Reinvestment Program handles both the same way. The fractional interest grows in lockstep with each declared payout.
One timing detail that catches people off guard is that a dividend instruction change must be submitted before the record date; otherwise it will not affect the upcoming payment. If you update the setting after that cutoff, the election applies only to the next cycle, which matters when a business announces a payout with a short window between the announcement and the record date. You have little room to adjust your preference if you want the cash to compound automatically, so check the record date first, then make your election before that deadline.
The process for how do i activate the dividend reinvestment on my fraction of stocks in Fidelity is documented through the Fidelity web flow. Under Account Features, expand Brokerage & Trading, then select Dividends and Capital Gains. Use Manage dividends, then Manage settings, and set Reinvest in security for Stocks, ETFs and others as well as mutual funds.
Reinvesting dividends at Schwab and Vanguard
When you want to reinvest dividends with Schwab, the toggle lives on the Positions page under the Accounts tab, where each holding shows a Reinvest? column. Click the Yes or No link to open a pop-up, select Yes, and hit Update; that election applies to that specific security. If you are placing a fresh buy order on the website, check the Reinvest Dividends box before submitting the trade to catch the position from the very first payout. Because the setting is per-security rather than account-wide, a stock ETF and a money-market fund sitting in the same portfolio can follow completely different compounding paths. To reinvest dividends with Vanguard, you enroll through the Vanguard Brokerage dividend reinvestment program. The key eligibility detail that trips people up is that not every security in your account qualifies; an ineligible holding simply pays cash to your settlement fund regardless of your overall preference, so you will want to verify that the specific asset you intend to compound is on the supported list before the record date passes.
Earning compound interest and growing your income
When you leave dividends in cash, growth stays linear, you collect the same payout on the same number of shares quarter after quarter. The moment you redirect that money back into the position, the math shifts because each new fractional or full share becomes a tiny additional earner in the next cycle. To earn compound interest on stocks, you typically enroll in a dividend reinvestment plan, which takes the cash payment and automatically buys more of the same stock or ETF so the following payout lands on a slightly larger holding. The tax treatment does not change with reinvestment because the IRS still considers the dividend received in cash and then used to purchase additional shares, so you carry the same tax obligation either way.
What makes the compounding uneven in practice is that a stock ETF pays only when the underlying businesses announce, while a money-market fund accrues income daily and pays monthly. A company that remits every three months can sit unchanged for months, then suddenly add shares, whereas a daily accrual position grows its base a little every single day. That split means the compounding curve for an equity portfolio rarely looks smooth on a short-term chart. Over years, however, the effect of reinvested shareholder payouts on total return becomes the dominant story. Lock in the reinvestment election before the cutoff set by your brokerage, which may be the dividend pay date, because missing that window leaves cash sitting idle until the next announcement rolls around.